My name is Edith Harwood, and for thirty-one years I have lived in the same house where my husband, Thomas, and I raised our children.
The walls have seen birthday candles, school projects, arguments over curfews, and thirty-eight years of ordinary evenings at our kitchen table.
Thomas died eighteen months ago. Some mornings I still reach for a second coffee mug before remembering that his chair is empty. I thought the hardest part of widowhood would be learning to live alone, but I had not anticipated having to defend the future we had built together.
Before Thomas died, we established three separate trusts for our grandchildren, each initially funded with $150,000. The money was intended for their benefit when they turned twenty-five, with provisions for qualifying educational and medical needs before then. I agreed to serve as trustee and follow those instructions.
It was not a reward for Michael and Rebecca, or an emergency fund for their household. Thomas and I had worked hard to save it because we wanted the children to begin adulthood with choices that we never had. We believed the restrictions would protect them.
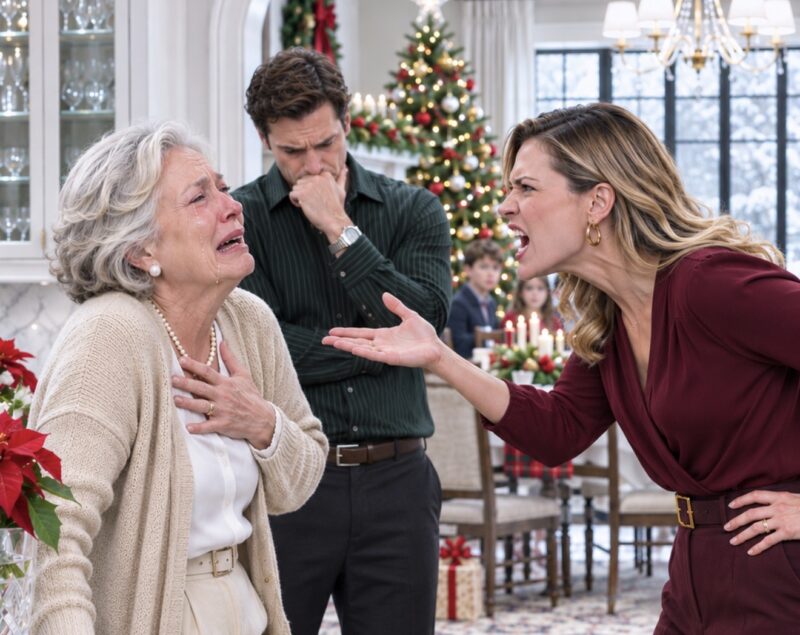
On Thanksgiving afternoon, Rebecca asked me to step into the hallway while the children played in the living room. She wore the pleasant smile she used when greeting people at parties, but her words sounded carefully rehearsed. Michael stood near the doorway, close enough to hear everything.
“Edith, Michael got a promotion. We’ve found a beautiful house in Worthington, with wonderful schools and plenty of room for the children.”
“That sounds lovely, Rebecca. I’m glad things are going well.”
“It’s listed for $890,000. We need help with the down payment, and we’d like to use some of the children’s trust money. You’ll need to transfer the trustee designation.”
I stared at her, certain I had misunderstood. A house could be a good place to raise children, but a parent’s desire for a larger home did not turn protected trust funds into a down-payment account. I explained that as calmly as I could.
“Those accounts aren’t available for buying a house. Thomas and I made that clear when we created them.”
“We’re their parents, Edith. We know what’s best for them. We’ve even spoken with a financial attorney. You only need to cooperate.”
“No, Rebecca. I won’t transfer control or approve money for that purpose.”
Her smile vanished. She told me Michael was earning more now and that they did not need me interfering in their finances. Then she said I was making their lives difficult because I wanted to control the family, as though I had invented the trust restrictions to spite her.
I turned toward my son. Michael would not meet my eyes, and I could see that he had expected me to give in. The silence from the boy I had raised hurt more than Rebecca’s accusations, because I knew he understood what his father had wanted.
“Michael, do you agree with her?”
“Mom, Rebecca’s trying to do what’s best for our family. Can’t you just help us this once?”
I had helped them many times. Over six years, my accountant had recorded $87,000 in gifts and assistance, including $40,000 toward their wedding. I had covered daycare bills, repairs, groceries, a mortgage emergency, and even a vacation when they said they needed time together.
I had never asked for repayment or used those gifts to win an argument. Yet the look on Michael’s face told me that what I considered generosity had become part of their financial expectations. My refusal now seemed to offend them more than all my previous help had pleased them.
“I love you both, but the trusts are not yours to spend.”
“Then stay out of our finances,” Rebecca replied. “We’re capable adults.”
I opened the front door and wished them a safe trip home. Michael gathered the children without saying goodbye properly, and Rebecca walked past me with her chin raised. I stood on the porch until their car disappeared, then returned to a kitchen that suddenly felt unbearably quiet.
Thomas’s chair was opposite mine. I sat there remembering how he used to spread the household bills across the table, insisting that we plan for the unexpected before spending on things we merely wanted. I opened the trust folder and called our attorney that evening.
“I want the three accounts protected. Please review the records and make sure nobody can change anything without following the agreements.”
“The restrictions are already in force, Edith. We’ll document your concerns and check the procedures for any requested changes.”
I slept badly, but the next morning I called Victor, our longtime financial adviser. He confirmed that no money had been transferred and the accounts remained intact. I thanked him, relieved, until his voice became quieter and he asked how much I knew about Rebecca’s earlier inquiries.
“She contacted this office three weeks before Thanksgiving,” he said. “She wanted to know how you could be replaced as trustee.”
“Replaced? She never mentioned that to me.”
“When our staff explained the applicable consent procedure, she asked who would take control if you became incapacitated or were declared legally incompetent. I have the question in our notes.”
I stared at the photograph of Thomas beside the telephone. Asking about succession was not, by itself, proof of an evil plan; sensible families discussed those things. But Rebecca had asked in secret, before confronting me, and in connection with a request for money the trusts did not permit.
My Daughter-In-Law Had Been Looking For A Way Around My Authority Before She Ever Asked Me For A Dollar.
“Victor, has she requested anything else?”
“She has asked about early distributions and whether the agreements might be modified. I think you and your attorney should review the correspondence.”
I called Rachel, my daughter, and told her what Victor had said. She came over carrying groceries, listened without interrupting, and asked to see the trust documents. Unlike Michael, she did not begin by telling me how Rebecca might feel; she asked whether the grandchildren’s money was safe.
“Victor says every account is intact,” I assured her. “But I don’t understand why Rebecca asked about my competency.”
“Then don’t guess, Mom. Get the notes, talk to your attorney, and protect yourself as well as the children.”
The next day Rachel brought a printed listing for the Worthington house. Its photographs showed tall windows, immaculate landscaping, and a staircase large enough for a hotel. Beneath the pictures was the price, $890,000, and Rachel had calculated a twenty-percent down payment of $178,000.
The number explained why Rebecca was so determined. The children collectively had $450,000 set aside, and their parents were looking at it as if it were a pool of cash available to rescue a purchase they could not otherwise afford. I folded the listing and put it in my folder.
“There’s nothing wrong with wanting a beautiful house,” Rachel said. “But they have to be able to pay for it.”
“Your father and I bought what we could afford. We never treated someone else’s future as our down payment.”
Victor called again that week. Rebecca had asked whether the children could receive an advance against their eventual distributions for a major family expense. He had explained that the trusts did not permit the arrangement she described, and she had asked whether I could simply make an exception.
I forwarded his notes to my attorney. He cautioned me not to turn a series of suspicious questions into accusations we could not substantiate. The appropriate response was to document the inquiries, follow the trust terms, and review the successor provisions so the children would remain protected if I ever became unable to serve.
That advice helped me think clearly. I had worked in hospital administration for thirty years, where procedures existed because good intentions did not replace accountability. If a department had requested restricted funds for an unauthorized purpose, I would never have released them merely to avoid an unpleasant conversation.
Yet I had been tempted to apologize to my own son for doing exactly what Thomas and I had agreed to do. I realized how much guilt had shaped my decisions since Thomas died, and how often I had paid a bill because I feared disappointing someone.
I met my attorney to review my retirement accounts, savings, property, and the informal assistance I had been providing. He explained that past generosity did not oblige me to continue supporting another household. I told him I wanted to stop treating every request from Michael as an automatic payment.
“You can still choose to give a gift when you want to,” he said. “But it should be your decision, not an assumed line in their budget.”
“Then that’s what I want. No more automatic help, and no promises made under pressure.”
A few evenings later Michael called. Rebecca had learned I was reviewing my finances, and she was furious. He said she felt attacked because I was involving professionals and keeping copies of their messages. I reminded him that his wife had been contacting Victor about replacing me.
“You’re making Rebecca sound like a terrible person,” he complained. “She was only frustrated.”
“I’m describing what she did, Michael. Frustration doesn’t change the words she used or the questions she asked.”
“Are you really going to stop helping us financially? We’ve been counting on that help.”
There it was, spoken aloud. They had built their plans around money I had never promised to provide indefinitely. When I explained that my retirement savings belonged to me and the trusts belonged to the children under their agreements, Michael ended the call abruptly.
The following morning Rebecca sent a message saying she hoped I understood the consequences of refusing to support their family. A later message was more direct: if I continued obstructing them, I should not expect to see the grandchildren. I saved both messages and forwarded them to my attorney.
The Most Painful Threat Wasn’t About Money—It Was The Suggestion That I Had To Buy My Place In My Grandchildren’s Lives.
For several days I heard nothing from the children. I missed the ordinary telephone calls, the school photographs, and my grandson’s habit of asking whether I had made butternut squash soup. I knew they were not responsible for the adults’ disagreement, and I refused to question them about it.
Rachel visited often. She helped me organize correspondence and reminded me that I could love Michael without accepting every demand he made. One afternoon she asked whether I would forgive him if he apologized, and whether forgiveness would mean reopening my checkbook.
“I would give him a chance to rebuild our relationship,” I said. “But the money is a separate matter.”
“Good,” she answered. “I wanted to hear you say that.”
Michael eventually asked to come over alone. He looked exhausted and sat in the living room without removing his jacket. For a while he spoke about work, then asked whether Rebecca had really contacted Victor before Thanksgiving. She had told him those inquiries happened only after my refusal.
I showed him the dated notes. He read the question about replacing me, then the question about legal incompetence. He looked up slowly, surprised, and asked why his wife would have needed that information. I told him he would have to ask her, because I could not claim to know her intentions.
“She didn’t tell me any of this,” he said. “I thought she was just asking about the rules.”
“You should have asked more questions before you took her side.”
“I know. Are the children’s accounts still safe?”
“Yes. Nothing has been taken, and the existing restrictions remain in place.”
I showed him the threatening message as well. He stared at it and asked why I had not told him. I reminded him that I had, and that he had dismissed my concern by saying Rebecca was upset. He rubbed his face, then admitted he should have asked to see the actual words.
He left without making promises, but something had shifted. A few days later he brought the children to visit. My grandson ran through the doorway shouting for me, and my granddaughter showed me a school project. I hugged them both and kept the afternoon free of adult grievances.
We ate soup at the kitchen table. Michael helped carry bowls, and the children asked whether they could return the following Saturday. When they left, I felt both grateful and cautious. One peaceful afternoon was a beginning, not proof that the pressure had ended.
Then Michael called with news: they were no longer pursuing the Worthington house. Their financing did not work as they had hoped, and Rebecca was angry. She blamed me for the lost opportunity, but Michael finally admitted that refusing to use restricted money was not the same as preventing them from buying a home.
I hoped that would end the argument. Instead, my attorney received a request from a lawyer representing Michael and Rebecca. They wanted a formal discussion about the trustee structure and the parents’ ability to participate in decisions affecting the children. I agreed to a meeting with the appropriate professionals present.
Rachel drove me to the office. Victor joined us with the account records, and my attorney laid out the three separate agreements. Michael and Rebecca arrived carrying a folder of their own. Rebecca looked composed, but she avoided looking at me as we sat around the conference table.
My attorney explained that the children’s beneficial interests were separate and that distributions had to satisfy the specific trust provisions. Parents could submit qualifying requests, but their preference for a different trustee or a more expensive house did not change the governing terms.
“We’re their parents,” Rebecca insisted. “We make decisions about their education and future. Why shouldn’t we have a say?”
“You may request distributions that the agreements permit,” Victor replied. “But a house purchase by the parents is not automatically an eligible expense.”
“Edith is holding the money over our heads. She could make this easier if she wanted to.”
“I have responsibilities under the agreements,” I said. “I cannot rewrite them because you dislike the answer.”
My attorney placed Victor’s dated communication notes on the table. He carefully explained that the inquiries were documented facts, not proof of Rebecca’s motives. Then he read the sequence: replacement of the trustee, succession in the event of incapacity, possible early distributions, and modifications.
Rebecca’s face tightened. She said she had only asked hypothetical questions and was entitled to understand the documents. Victor agreed she could ask, but explained that he had given accurate answers and preserved the records. Michael stared at the dates, realizing the calls had begun before Thanksgiving.
When The Attorney Laid Out The Timeline, My Son Finally Saw How Long The Pressure Had Been Building Behind My Back.
Then Michael noticed the printed message about keeping the children away from me. He picked it up, read it twice, and turned toward Rebecca. For the first time, he seemed more concerned about what she had actually written than about defending her embarrassment.
“Did you tell my mother she wouldn’t see the kids again?”
“I was upset,” Rebecca answered. “I wanted her to understand that her decisions affected us.”
“You used our children to threaten her,” he said. “I didn’t know you wrote that.”
I did not enjoy watching them argue. I had wanted my son to understand, not to see my family humiliated in a conference room. My attorney brought the conversation back to the agreements and confirmed that no unauthorized transfers had occurred and no change would be made simply because the parents requested one.
 Any future requests would follow the documented approval process, and questions about trustee succession would be addressed according to the governing provisions. My attorney also reviewed continuity planning with me, so the accounts would remain properly administered if I could no longer serve.
When the meeting ended, Rebecca gathered her folder and told me she hoped I was happy. I said I was not happy we had needed the meeting, only relieved that the children remained protected. She left first, while Michael stayed behind near the doorway.
“Mom, I’m sorry. I should have asked to see the messages, and I should have listened to you.”
“I love you, Michael. But we cannot go back to the way things were.”
He asked what that meant, and I told him I wanted family visits that were not negotiations over money. I would not automatically pay their bills, and I would not accept threats involving the children. He nodded, then hugged me awkwardly before leaving.
Over the next few weeks, Michael began visiting more regularly with the children. Rebecca stayed away at first. I did not press for explanations, and I did not ask Michael to report on his marriage. I focused on making my home a place where the children felt welcome and safe.
One Sunday, Rebecca finally came with him. We sat at the kitchen table while the children played nearby. She said the house had put them under pressure and that she had felt excluded from decisions affecting her own family. I listened, but I did not agree that the trusts were hers to control.
“I shouldn’t have sent that message,” she admitted. “I was angry, and I handled it badly.”
“The children cannot be bargaining tools,” I told her. “If you disagree with me, we can talk. But you cannot make their love conditional on a financial decision.”
She nodded, though I could not tell how much she truly accepted. There was no dramatic embrace and no promise that everything would suddenly be perfect. Afterward, my granddaughter asked whether we could bake cookies, and for an hour the kitchen was filled with flour and ordinary laughter.
Meanwhile, my attorney completed a review of my retirement and estate arrangements, and Victor continued to confirm that the three trusts were intact. The children still had the protected future Thomas and I intended. Michael and Rebecca would have to manage their household without assuming my savings were theirs.
Rachel and I began planning a short trip. I had postponed traveling after Thomas died because enjoying anything without him felt disloyal. Now I understood that living fully was not the same as forgetting him, and that I had spent too much time waiting for my family’s approval.
One afternoon I visited Thomas’s grave with flowers. I told him about the children, the difficult meetings, and the little steps Michael had taken. I admitted that I still missed his advice, especially when a decision left me wondering whether love required another sacrifice.
I remembered something he used to say when our children were young: a family was not measured by how often people agreed, but by how they treated one another when they did not. I finally understood that protecting a boundary could be an act of love rather than its opposite.
When I returned home, Michael had sent a message asking whether the children could visit the next day. I smiled and replied that I would make soup. They arrived with school projects, stories, and hungry appetites, and nobody asked me for money.
That evening, after they left, I sat across from Thomas’s empty chair and looked at the folder on the shelf. Inside were three trust agreements, three protected futures, and proof that I had kept a promise to the man I loved.
Rebecca had told me to stay out of their finances. In the end, I did exactly that: I stopped paying their expenses and let them make their own choices. But I never abandoned my duty to the grandchildren, and I never surrendered my right to say no.
I still love Michael. I hope Rebecca and I can build a more respectful relationship, and I will always welcome the children. What changed was not my love for them, but my belief that love had to be purchased with money, silence, or fear.
For the first time since Thomas died, the quiet house felt peaceful again. I turned off the kitchen light, touched the back of his chair, and went upstairs knowing that I had protected not only the children’s future, but my own.
THE END.